
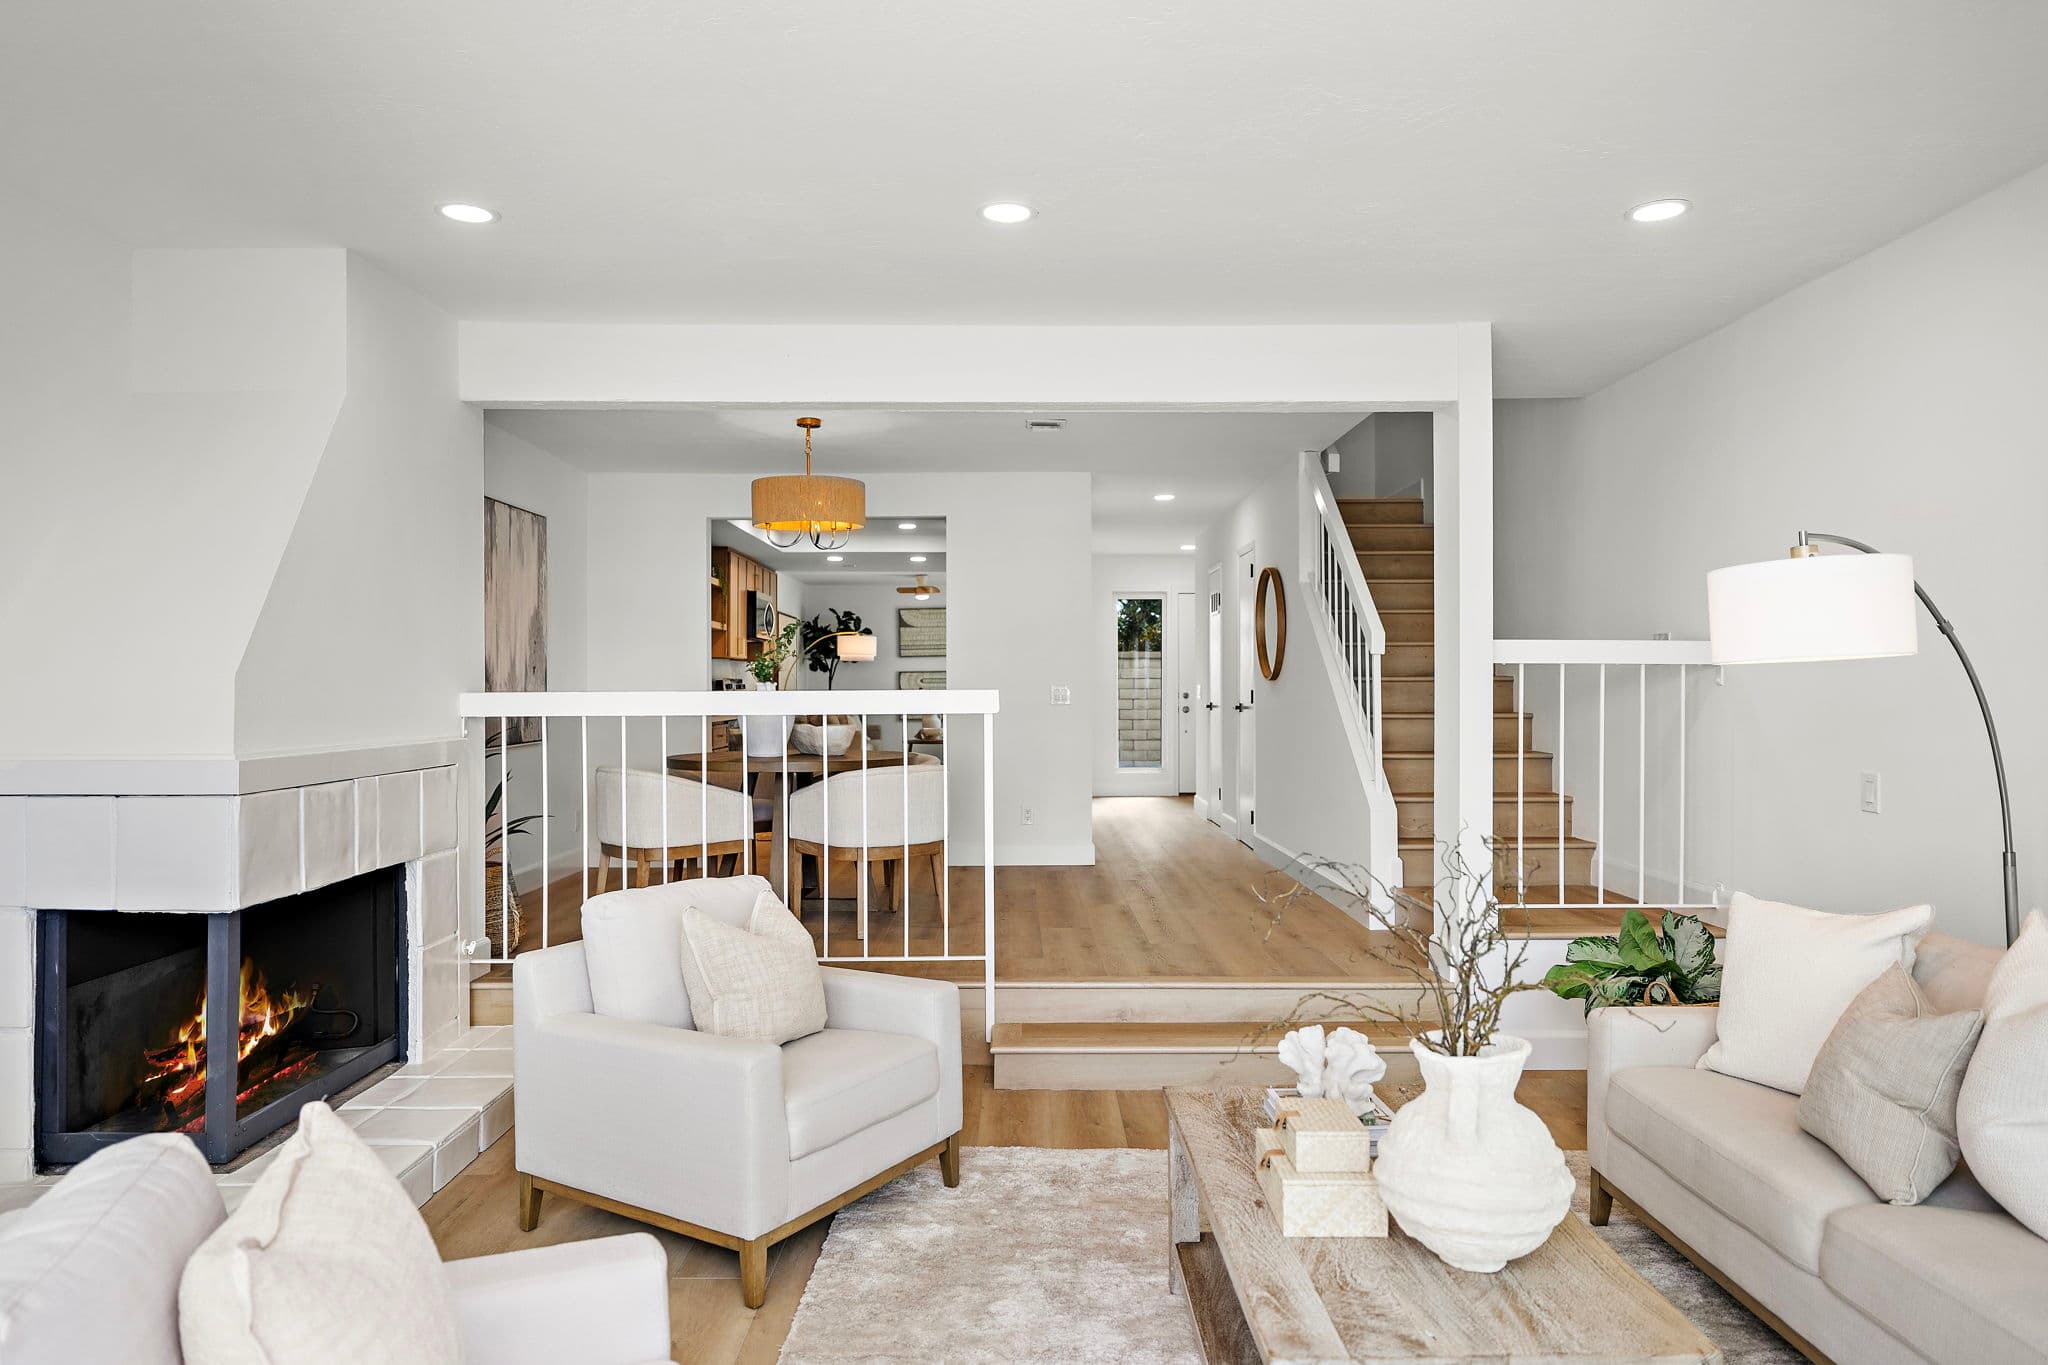
Buying a condo in Huntington Beach: a complete guide
Lower maintenance, real coastal access, and a few questions that matter more than the granite. Here's how to buy a condo here the right way.
Direct answer
A condo in Huntington Beach buys you coastal access and lower maintenance, often from the high six figures to around $1.5M depending on location and the building. The home itself matters less than the HOA behind it, so the real diligence is reading reserves, special-assessment history, litigation, rental caps, and whether the building is warrantable for your loan. Ratowsky Group at Compass reviews the HOA documents and the specific community with you before you write an offer.
Updated 2026-06-24
At a glance
Typical price band
High six figures to ~$1.5M
Wide spread by location, square footage, and whether it's near the sand.
What you're really buying
The HOA, not just the unit
Reserves, dues, and rules shape the cost and the resale more than the finishes.
Financing check
Warrantable vs non-warrantable
Lender review of the whole project can change your loan, rate, or down payment.
Monthly math
Dues + taxes
HOA dues and special taxes vary by community and move the real payment.
Start here
A condo here is a lifestyle trade, not a consolation prize.
Plenty of people choose a Huntington Beach condo on purpose, not because a single-family home priced them out. You get coastal access, a lock-and-leave home that doesn't eat your weekends, and in a lot of cases a pool, a gate, or a spot near the pier you'd pay a lot more to own as a detached house. For a first home, a second home near the water, a 55-plus move, or anyone who'd rather surf than mow, that trade makes sense.
The constraint is ownership. You own your unit and a slice of the common areas, and you live by the rules the HOA sets: what you can change, whether you can rent it out, where you park, what you pay every month. None of that is bad. It just means the building you buy into matters as much as the unit, sometimes more. A beautiful kitchen inside a financially shaky HOA is a problem wearing a nice outfit.
The map
Where condos and attached homes cluster in Huntington Beach.
Condos aren't spread evenly across town. Near the pier and Downtown you'll find walkable, close-to-the-sand attached homes like Pier Colony and the Boardwalk towers (Lighthouse, Shoreline, Nautical Pointe, and Mystic Pointe), where the premium is the location and the lifestyle that comes with it. These are the ones where you walk to the water and pay for the privilege.
Inland, the communities trade some proximity for space, dues that often cover more, and a calmer setting: Pacific Ranch behind its gates, Seabridge with its water features, Beachwalk near the wetlands, and Huntington Continental as one of the older, more established tracts. For 55-plus buyers, Huntington Landmark is the anchor, a large age-qualified community with its own clubhouse and amenities. Each of these prices differently, carries different dues, and attracts a different buyer pool, which is exactly why a citywide condo average won't tell you much about the one you're considering.
Real Huntington Beach condo and attached communities
- Near the pier / Downtown: Pier Colony, Boardwalk (Lighthouse, Shoreline, Nautical Pointe, Mystic Pointe)
- Inland & gated: Pacific Ranch, Seabridge, Beachwalk, Huntington Continental
- Age-qualified (55+): Huntington Landmark, with its own clubhouse and amenities
- Each carries its own dues, rules, and rental policies. Ask us for a current read on the one you want.
The monthly number
What HOA dues actually cover, and why they vary so much.
HOA dues are not a tax and they're not wasted money, they're how shared things get paid for. Depending on the community, your dues can cover the master insurance policy on the structure, exterior maintenance and roofs, landscaping, the pool and clubhouse, trash and water, gated entry, and the reserve fund that pays for big future repairs. A building near the water that covers more exterior upkeep will usually carry higher dues than an inland tract where you handle more yourself. Higher dues aren't automatically bad, and low dues aren't automatically good. What matters is whether the dues actually fund what the building needs.
Between dues, base taxes, and your loan, the real monthly number can look very different from the list price math. We're not lenders or tax professionals, so we'll get you a clear picture and then loop in your lender to confirm the financing side and the actual payment.
The real diligence
How to read whether an HOA is healthy.
When you go into escrow on a condo, you get the HOA documents, and this is where the actual work is. Four things tell you most of what you need to know. First, the reserve study and reserve balance: a well-run HOA sets money aside for roofs, plumbing, paint, and the rest, and a reserve that's funded near its target means owners aren't about to get surprised. A badly underfunded reserve is a special assessment waiting to happen. Second, special-assessment history: if owners have been hit with extra bills for repairs the reserves should have covered, that's a pattern, not a one-off.
Third, litigation. An HOA in active litigation, especially construction-defect litigation, can scare off lenders and complicate your loan, so you want to know what's pending and why. Fourth, the rental cap. Many communities limit how many units can be rented at once, and if you ever want to rent yours, or if a low owner-occupancy ratio is going to trip up your financing, you need that answer before you write the offer, not after. Craig has read decades of these files, and the questions he asks first are the ones that turn into problems later if nobody asks them.
Financing
Warrantable vs non-warrantable, and why your lender reviews the whole building.
Buying a condo isn't just the lender approving you, it's the lender approving the project. A warrantable condo meets the guidelines that conventional loans (think Fannie Mae and Freddie Mac) require: enough owner-occupants versus renters, no single owner controlling too many units, adequate reserves and insurance, and no disqualifying litigation. A non-warrantable condo fails one or more of those, and it's not the end of the road, but it usually means a different loan, a larger down payment, or a higher rate, because fewer lenders will touch it.
This is why the building you choose can change your financing before you've negotiated a dollar. A high renter ratio near the pier, an HOA in litigation, or a community with thin reserves can all push a project into non-warrantable territory. The fix is sequence: get pre-approved, then have your lender review the specific HOA early so there are no surprises at the appraisal. We coordinate that handoff so the building and the loan get vetted together, not separately. Again, we're not lenders, so the final call on warrantability and your loan is theirs, but we know which buildings tend to raise the question.
Before you offer
How to evaluate a specific building.
Once you've narrowed to an actual unit, the evaluation gets concrete. Walk the common areas, not just the unit: how the grounds, the pool, the hallways, and the parking actually look tells you whether the dues are being put to work or deferred. Ask how recently the roofs, plumbing, and major systems were done, and what's coming up in the reserve study. Notice the renter-to-owner feel of the place and confirm it against the documents. And look at how units in that specific community have sold and how long they sat, because resale liquidity is part of what you're buying.
This is where a local team earns its keep. We've sold inside these communities, so we know which Huntington Landmark floor plans hold value, how the Boardwalk towers price by floor and view, what the dues at Seabridge or Pacific Ranch actually buy, and which buildings have a clean diligence history. Two units that look identical online can be very different purchases once you read the HOA and walk the grounds. We'll tell you the difference before you fall for the staging.
Frequently asked
Condos, the questions we hear first.
How much does a condo cost in Huntington Beach?
What do HOA dues cover in a Huntington Beach condo?
How do I know if a condo HOA is financially healthy?
What does warrantable vs non-warrantable mean for a condo?
Are there 55-plus condo communities in Huntington Beach?
Can I rent out my Huntington Beach condo?
Why are HOA dues so different between Huntington Beach condo communities?
Is buying a condo in Huntington Beach a good idea?
Your Huntington Beach real estate team
Craig and Justin Ratowsky.
Craig Ratowsky and Justin Ratowsky are equal partners at Ratowsky Group, principal agents with Compass, and founding members of the Compass Huntington Beach office. Craig has sold Huntington Beach real estate since 1977, bringing 49 years of pricing and negotiation experience. Justin is a third-generation California Realtor® focused on local guidance and modern marketing. Together, they bring 58+ years of combined experience.
Sources & local citations
Qualitative claims framed as agent insight reflect Ratowsky Group’s direct experience and are not represented as third-party verified data.
Thinking about a condo?
Want a straight read on a Huntington Beach condo community?
Send us the building you're looking at and we'll give you a real take on the dues, the HOA, and how units there have sold. No pressure, just useful information.
Ratowsky Group at Compass. Craig Ratowsky DRE #00608046, Justin Ratowsky DRE #02026158. Guidance is general market context, not a valuation, tax, or legal advice.